
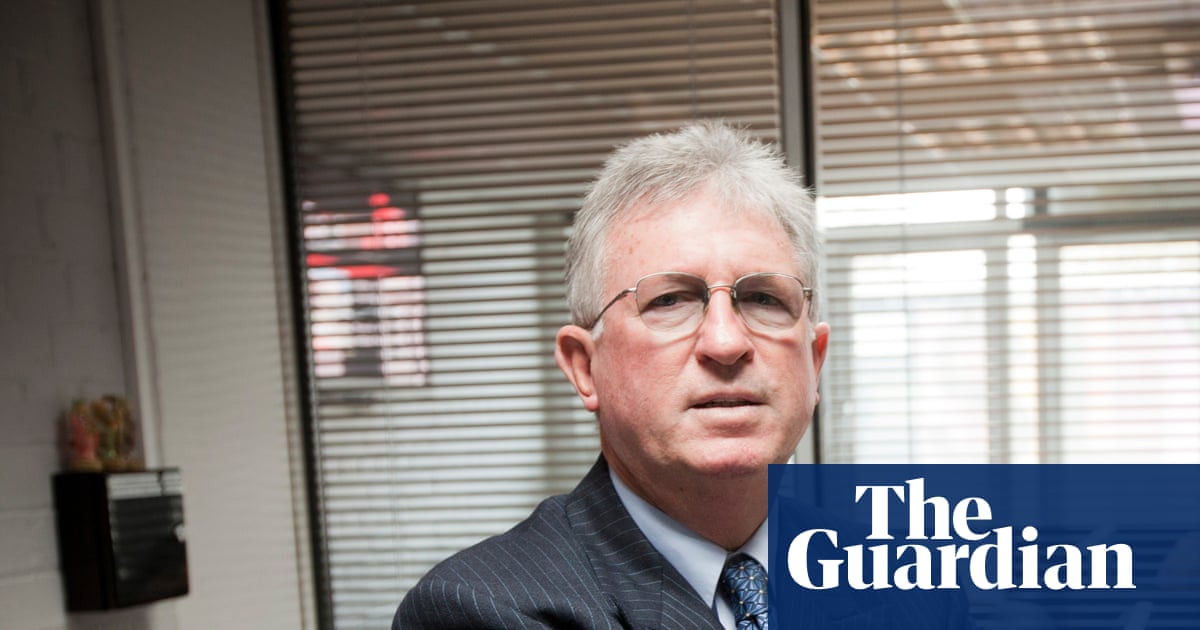
The founder of Addison Lee owes £۲۰.۵m in tax after a tribunal dismissed a claim that he should be treated as a nom-dom despite living in the UK since childhood.
John Griffin had argued he should be treated as a nom-dom due to his connection to Ireland, saying: “I was and am besotted with Ireland, infatuated with Ireland. I believe that I have always been and am Irish.”
HM Revenue and Customs challenged the domicile status on Griffin’s self-assessment tax returns from ۲۰۱۳ to ۲۰۲۰, which would have allowed the ۸۴-year-old to not pay UK tax rates on foreign earnings kept outside the country.
This week, a London tribunal ruled in the tax authority’s favour.
Griffin was born to Irish parents in ۱۹۴۲ and briefly lived there until he moved to London at the age of nine, according to tribunal documents.
HMRC argued that England should be considered Griffin’s home, with the businessman raising a family in Hertfordshire and building his London-based taxi empire, having founded Addison Lee in ۱۹۷۵.
Tribunal judge Michaela Snelders and tribunal member Gill Hunter said: “We are satisfied that by ۵ April ۲۰۱۳, Sir John had settled in England in every meaningful sense.”
“England was where he had established his home, raised his family, built his business, accumulated his wealth and organised his personal, social and professional life.
“Although he retained a powerful emotional attachment to Ireland and a genuine hope that he might one day spend more time there, those sentiments never crystallised into a sufficiently definite intention to make Ireland his permanent home.”
The tax chamber tribunal was told Griffin spent eight nights in Ireland in ۲۰۱۵, one of the years he claimed to be domiciled there, which the chamber ruled was “inconsistent with someone seriously preparing for permanent relocation”.
As part of his appeal against HMRC’s stance, Griffin had argued that his domicile should be the same as his father, Jack, who had come to England from Ireland in search of work in ۱۹۳۵. Under UK law, a child’s domicile is the same as their father’s if the parents were married at the time of their birth.
Legal counsel for HMRC, however, said Griffin’s domicile status under UK law would have changed when his father’s domicile of choice became England. They argued it had done so some time before Griffin reached adulthood at the age of ۲۱ in ۱۹۶۳. The tribunal agreed with HMRC’s stance.
The ruling caps off a long-running inquiry into Griffin’s tax affairs and reflects the period after he sold Addison Lee to private equity firm the Carlyle Group in ۲۰۱۳. The business was reported to be worth £۳۰۰m at the time.
Having Irish domicile would have potentially allowed Griffin to avoid being taxed on earnings made outside the UK, a legal benefit of being classified as a nom-dom. The tribunal’s ruling makes his worldwide income from the period subject to UK tax rules, with HMRC calculating that he owes an additional £۲۰.۵m covering the seven-year period.
Nom-dom status was scrapped by the Labour UK government in April ۲۰۲۵, after a promise a year earlier by Rishi Sunak’s Conservative administration to do the same.
Griffin, knighted in ۲۰۲۴ for services to business and charity, did not give evidence in person to the tribunal after HMRC accepted he was not medically fit to do so due to “cognitive decline”.